
4 November 2026
Global Bizjet Activity
Global bizjet activity fell 2.4% year-on-year in Week 44 (26 Oct – 1 Nov), with just over 74,000 departures operated globally. Halloween fell in Week 44 in both years, and while Halloween week is always quieter than a typical week in the US, this year’s dip was a little deeper than usual, but it could be attributed to Halloween falling on different days of the week. The Middle East was also hit by the postponement of Riyadh’s Future Investment Initiative (FII), which inflated last year’s comparison. The four-week trend has turned slightly negative at -0.5%, while the year-to-date figure stands at +3.0% ahead of last year through 1 November. North America slipped 1.6% and Europe 2.4%, while Central America (-21.7%) and the Middle East (-22.5%) remained the weakest regions last week.
On the fleet side, JETNET data shows 1,784 business jets listed for sale, 6.9% of the in-service fleet and up for a fourth consecutive week.
What Drove the Week
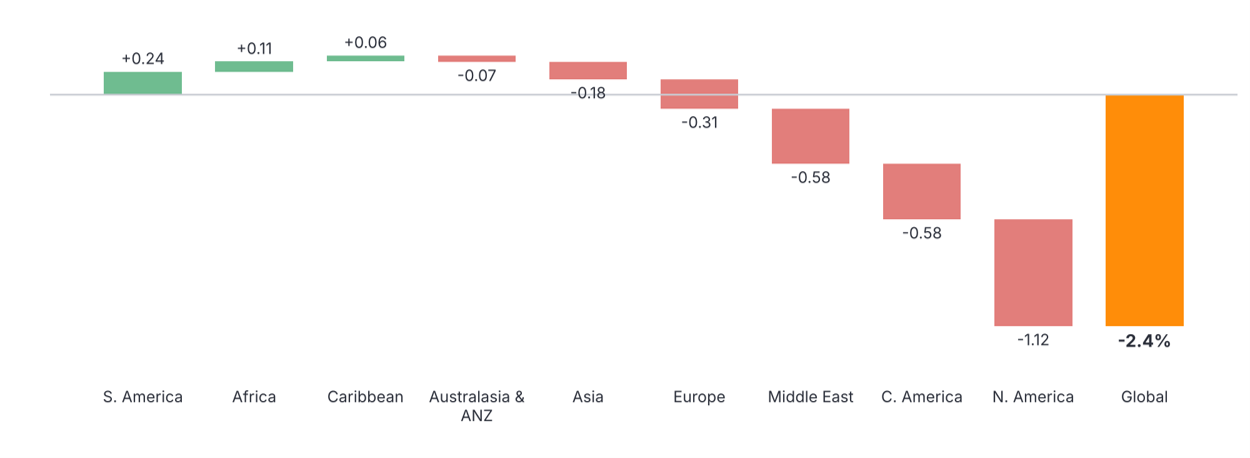
The chart below breaks global growth down by sub-region. North America took 1.12 points off global growth, while Central America and the Middle East each subtracted a further 0.58 points. South America (+0.24 points), Africa (+0.11 points) and the Caribbean (+0.06 points) were the only sub-regions to grow.
Chart 1: Contribution to global bizjet departures YOY growth by sub-region (Week 44 2026 vs Week 44 2025)
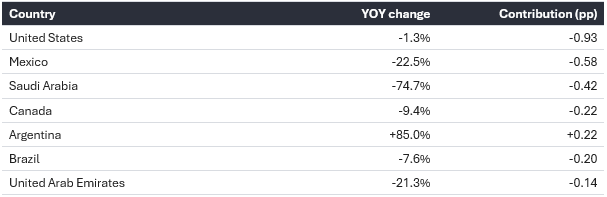
On a top country basis last week, the United States, down 1.3%, was the largest drag on global growth, followed by Mexico (-22.5%) and Saudi Arabia (-74.7%). Argentina (+85%) was the largest contributor to growth.
Table 1: Biggest country movers, Week 44 (26 Oct – 1 Nov)
Trend Context
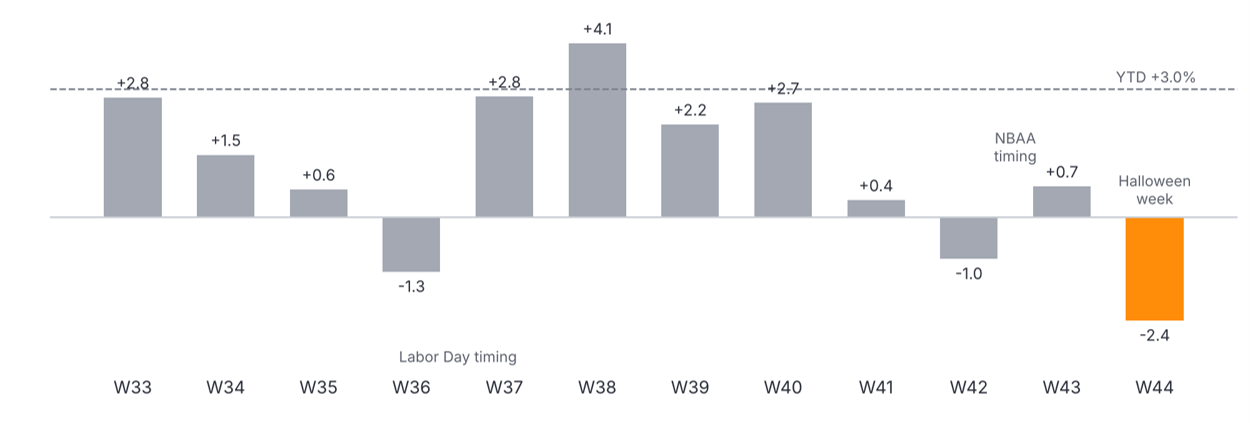
The chart below puts Week 44 in context. Weekly year-on-year growth held largely in a 2–4% range through the summer and early autumn, but has slowed to around zero over the last four weeks as 2026 is compared against the start of last year’s strong fourth quarter. Week 44 was the weakest week since early September.
Chart 2: Global business jet departures, YOY % change by week (Weeks 33 – 44, 2026 vs 2025)
Is Halloween week always quieter?
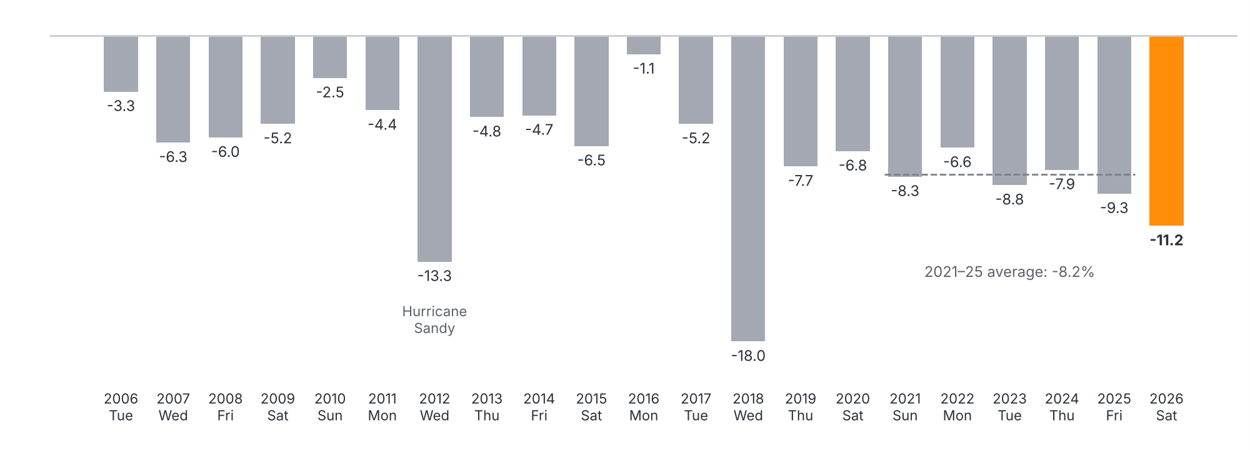
To see whether Halloween week is always weaker than a typical week, Chart 3 compares US business jet departures in the week containing Halloween with the average of the three weeks before it, for every year since 2006. Halloween week was lower in all 20 years from 2006 to 2025, whichever day Halloween fell on. The dip has deepened in recent years, averaging 8.2% from 2021 to 2025, and last year’s was 9.3%.
This year’s Halloween week was 11.2% below the previous three weeks, the deepest since 2018 and around 2–3 points weaker than the recent norm.
Chart 3: US business jet departures in Halloween week, % change vs the average of the previous three weeks, 2006 – 2026
Regional Performance Analysis in Week 44
Table 2: Bizjet departures by region, Week 44 and year-to-date (1 January – 1 November)
|
Region |
W44 departures |
W44 YOY |
YTD YOY |
|
North America |
53,347 |
-1.6% |
+4.2% |
|
Europe |
9,560 |
-2.4% |
+1.1% |
|
South America |
2,838 |
+6.9% |
+12.9% |
|
Asia |
2,448 |
-5.3% |
+2.0% |
|
Central America |
1,598 |
-21.7% |
-18.2% |
|
Middle East |
1,506 |
-22.5% |
-14.2% |
|
Africa |
1,090 |
+7.9% |
+6.7% |
|
Caribbean |
877 |
+5.8% |
+9.1% |
|
Australasia & ANZ |
747 |
-6.5% |
-4.8% |
North America
The North American market slipped 1.6% year-on-year last week, with just over 53,300 departures. The United States accounted for roughly 97% of North American flights (and around 70% of all global departures) with 51,699 flights, down 1.3%, while Canada fell 9.4%. As Chart 3 shows, Halloween week was a little quieter than usual in the US this year. Across the full week, New Jersey (+13.4%), Georgia (+8.1%) and Texas (+4.8%) grew, and Florida was flat, while California (-14.0%), Missouri (-12.6%) and Tennessee (-6.4%) declined. On a year-to-date basis, North America remains the anchor of global growth, up 4.2%.
Europe
European business jet traffic eased 2.4% year-on-year in Week 44 with just over 9,550 flights, and its year-to-date trend sits at +1.1%. Among the largest markets, the UK (+1.2%) and Spain (+2.4%) grew, while Germany fell 6.8%, France 2.6% and Italy 2.5%. Switzerland was down 10.4%, while Portugal (+13.7%) and the Netherlands (+11.9%) grew strongly.
Table 3: Bizjet departures by European country, Week 44 and year-to-date (1 January – 1 November)
|
Country |
W44 departures |
W44 YOY |
YTD YOY |
|
United Kingdom |
1,515 |
+1.2% |
+1.3% |
|
France |
1,287 |
-2.6% |
0.0% |
|
Germany |
1,160 |
-6.8% |
-2.5% |
|
Spain |
1,152 |
+2.4% |
+4.8% |
|
Italy |
1,050 |
-2.5% |
+4.3% |
|
Switzerland |
571 |
-10.4% |
+2.3% |
|
Austria |
245 |
-7.9% |
-3.3% |
|
Sweden |
243 |
-8.6% |
-3.9% |
|
Portugal |
208 |
+13.7% |
+6.4% |
|
Netherlands |
207 |
+11.9% |
+1.0% |
|
Greece |
206 |
-3.3% |
+3.1% |
|
Belgium |
185 |
+3.4% |
-3.2% |
Our airport activity analysis shows that Paris Le Bourget remained Europe’s busiest business aviation airport but fell 14.9% year-on-year, potentially the result of continued riots. Geneva (-17.0%), London Luton (-16.2%) and Milan Linate (-13.9%) also declined, while Farnborough (+14.2%), Barcelona (+10.8%) and Amsterdam Schiphol (+38.0%) grew.
Table 4: Busiest European airports by bizjet departures, Week 44 2026 vs Week 44 2025
|
Airport |
W44 2026 |
W44 2025 |
YOY change |
|
Paris Le Bourget (LFPB) |
354 |
416 |
-14.9% |
|
Farnborough (EGLF) |
281 |
246 |
+14.2% |
|
Nice (LFMN) |
255 |
242 |
+5.4% |
|
Geneva (LSGG) |
229 |
276 |
-17.0% |
|
Madrid Barajas (LEMD) |
216 |
219 |
-1.4% |
|
London Luton (EGGW) |
212 |
253 |
-16.2% |
|
Milan Linate (LIML) |
198 |
230 |
-13.9% |
|
Zurich (LSZH) |
188 |
183 |
+2.7% |
|
Rome Ciampino (LIRA) |
178 |
164 |
+8.5% |
|
Palma de Mallorca (LEPA) |
176 |
163 |
+8.0% |
|
London Biggin Hill (EGKB) |
158 |
146 |
+8.2% |
|
Barcelona (LEBL) |
144 |
130 |
+10.8% |
Rest of World
Outside Europe and North America, Africa (+7.9%), South America (+6.9%) and the Caribbean (+5.8%) grew. South America’s gain came from Argentina (+85%) and Venezuela (+83%), offsetting a 7.6% decline in Brazil. Asia fell 5.3% and Australasia & ANZ 6.5%.
Mexico, which is the main contributor to the decline in Central America, fell 22.5%, and as in previous weeks the decline was in domestic flying rather than cross-border traffic. Flights within Mexico fell 33% year-on-year, while international departures were down only 2%. Domestic flights by US-registered jets more than halved, and Mexican-registered domestic flights fell 23%. Toluca, the country’s busiest business aviation airport, fell 22%.
Table 5: Mexico bizjet departures by flight type and aircraft registration, Week 44 2026 vs 2025
|
Flight type |
Registration |
W44 2026 |
YOY change |
|
Domestic |
Mexico |
655 |
-23% |
|
Domestic |
United States |
187 |
-53% |
|
International |
Mexico |
238 |
+5% |
|
International |
United States |
386 |
-6% |
At route level, the decline was centered on Toluca. Routes into and out of Toluca lost 208 flights (-25%), almost half of Mexico’s total decline, and nine of the ten biggest-losing routes connected Toluca with regional cities and beach destinations. Acapulco – Toluca fell from 79 to 28 flights, followed by Guadalajara – Toluca (-32), Toluca – Manzanillo (-21) and Monterrey del Norte – Toluca (-20). Domestic flying away from Toluca fell by a similar 33%, while flights between Mexico and the US were broadly flat. Cross-border routes into Los Cabos were among the few to grow, with Van Nuys – Los Cabos up from 3 to 14 flights.
Part of the Acapulco drop is calendar timing. Last year, the Day of the Dead holiday (1–2 November) fell on a weekend inside Week 44, and Acapulco – Toluca flights doubled from a normal 36–42 a week. This year 2 November fell on a Monday, moving the return flights into Week 45. Domestic flying in Mexico was also down 37% the week before, so the holiday shift explains only a small part of the decline.
Table 6: Biggest-losing Mexico bizjet routes, Week 44 2026 vs Week 44 2025
|
Route |
W44 2025 |
W44 2026 |
Change |
|
Acapulco – Toluca |
79 |
28 |
-51 |
|
Guadalajara – Toluca |
73 |
41 |
-32 |
|
Toluca – Manzanillo |
25 |
4 |
-21 |
|
Monterrey del Norte – Toluca |
52 |
32 |
-20 |
|
Puebla – Toluca |
21 |
4 |
-17 |
|
Monterrey – Toluca |
59 |
42 |
-17 |
|
Oaxaca – Toluca |
27 |
11 |
-16 |
|
Laredo (US) – Querétaro |
18 |
5 |
-13 |
|
Mérida – Toluca |
19 |
8 |
-11 |
|
Querétaro – Toluca |
25 |
15 |
-10 |
Mover of the Week: FII postponement in Riyadh
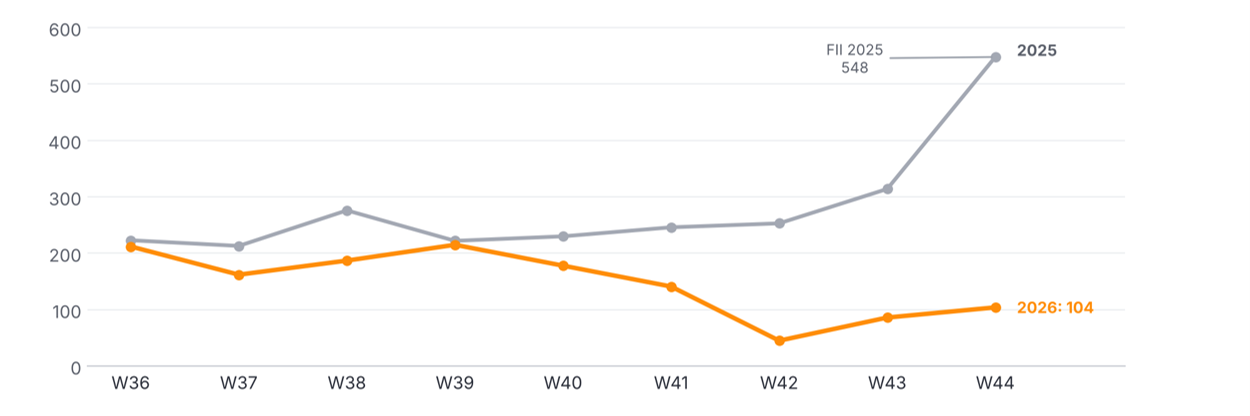
The Middle East fell 22.5% in Week 44, and Saudi Arabia alone took 0.42 points off global growth, with departures down 75%. Last year, Week 44 coincided with the Future Investment Initiative in Riyadh, which drew a surge of business jet traffic: movements at Riyadh’s airports reached 548 that week, around double the usual level. This year’s edition, planned for 26–29 October, was postponed to 2027, and Riyadh movements were just 104.
Chart 4: Business jet movements at Riyadh airports (OERK, OEKK) by week, 2025 vs 2026
Gulf departures as a whole fell 44%; excluding Saudi Arabia, the decline was 27%, broadly in line with recent weeks. The UAE fell 21.3%.
Who Is Flying
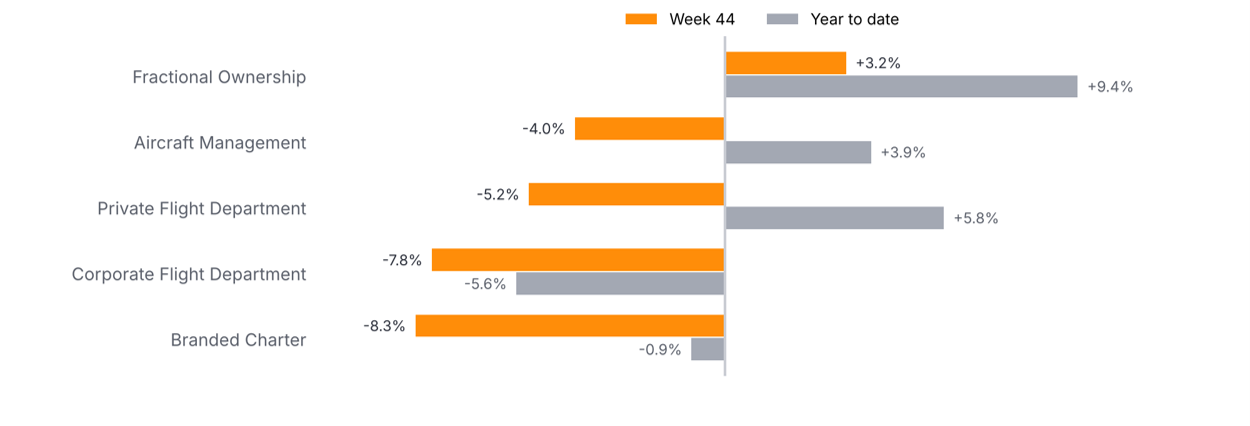
Fractional operators were again the only major operator type to grow, up 3.2% in Week 44. Aircraft management fell 4.0%, private flight departments 5.2% and corporate flight departments 7.8%. In contrast, branded charter demand fell 8.3%, its fourth consecutive weekly decline, with North America down 8.3% and Europe 5.7%. Year-to-date, fractional activity remains the strongest segment, up 9.4%, followed by private flight departments (+5.8%) and aircraft management (+3.9%), while corporate flight departments are down 5.6% and branded charter 0.9%.
Chart 5: Business jet departures YOY % change by operator type, Week 44 and year-to-date (1 January – 1 November)
Fleet Lens
Combining WINGX flight data with JETNET fleet records, in Week 44, the number of active jets slipped 0.7% in Week 44, while departures per active jet fell 1.8% and flight hours per jet 1.1%. The number of jets listed for sale rose for a fourth consecutive week, to 1,784, and new listings rose to 67.
Table 7: Business jet fleet and utilisation, Week 44
|
Measure |
Value |
vs last year |
|
Business jets in service (JETNET) |
25,765 |
– |
|
Jets that flew in Week 44 |
13,429 (52.1% of fleet) |
-0.7% |
|
Departures per active jet |
5.51 |
-1.8% |
|
Flight hours per active jet |
9.2 |
-1.1% |
|
Active airframes, year-to-date |
23,075 |
+2.5% |
|
Jets for sale (JETNET) |
1,784 (6.9% of fleet) |
– |
|
New listings, Week 44 (JETNET) |
67 |
– |
Looking Ahead to Week 45
- Post-Halloween recovery: with the Halloween lull out of the comparison, Week 45 will show whether last week’s softness was a one-off.
- Fleet supply: jets for sale have risen for four weeks running; a continued build-up would point to softening pre-owned demand.
- Fourth quarter: comparisons stay tough through November, when growth reached +9.4% in 2025.
Conclusion
Nick Koscinski, WINGX Analyst, comments, “Global activity was down 2.4% last week. Halloween week is always quiet in the US, and this year’s was a bit quieter than usual, plus the postponed FII conference in Riyadh sitting in last year’s numbers. Fractional is still the bright spot, while charter continues to dip. On the fleet side, jets for sale have edged up for four straight weeks to 1,784, which is worth watching as we head into year-end.”
Note: Figures cover business jets including VIP/bizliner aircraft. All figures exclude turboprops.
Want to dig deeper into these insights and scale your business with confidence?
WINGX is the global online aviation insights solution that helps professionals understand business aviation activity, benchmark their performance, and spot change across the industry.
Recent Platform Improvements:
AI Search
Enables users on the main dashboard to ask an Air insights question to WINGX. Users can specify the parameters and filters for their question and get a clear and structured answer back.
If users have a subscription to both WINGX Enterprise and JETNET Marketplace Live, then they can ask questions and get answers back from either database.
Available to WINGX Enterprise subscribers only.
MCP Integrations
All WINGX data is now available within Claude, Co-pilot, and Gemini, with more on the way.
Available to WINGX Enterprise subscribers.
Expansion of Ramp Monitor
Ramp Monitor now covers 230 airports, with more than 130 airports with a polygon conversion of >90%.
Find out more about Ramp Monitor for FBOs here.
Operator Names
We have further optimized how operator names are searched and filtered within the WINGX database.
Each operator name is now confirmed against four independent sources:
- Our operator master list
- The ICAO designator list (by callsign)
- JETNET Aerodex database
- Aircraft registry (by aircraft registration)
This means that operator names will have consistent spelling and honorifics, and are shown at the level that flies the aircraft. For example: VistaJet by AOC (Malta, America, Germany).
Find out more here.
